Canada’s technology industry generated over $230 billion in revenue in 2025 and employs nearly 1.8 million professionals, positioning the sector as one of the nation’s most critical economic engines. The industry’s competitive advantage rests on three pillars: world-leading artificial intelligence research anchored by institutions like the Vector Institute and Mila, a robust talent pipeline fed by top-tier universities, and government policy frameworks that incentivize innovation through programs like the Scientific Research and Experimental Development tax credit.
Yet scale remains the defining challenge. While Canada excels at launching startups and pioneering breakthrough research, too many companies sell to foreign acquirers before reaching global maturity. The country ranks third globally in venture capital invested per capita but struggles to retain the intellectual property and headquarters of its most successful ventures. This pattern is reshaping Canadian industry in ways both promising and concerning.
Six subsectors drive the current landscape: artificial intelligence and machine learning, where Toronto-Waterloo and Montreal lead global research; clean technology, where companies are commercializing solutions for energy transition; financial technology, with Toronto emerging as North America’s third-largest fintech hub; health technology, accelerated by pandemic-era digital transformation; quantum computing, led by ventures spun out of University of Waterloo; and enterprise software, where Canadian firms serve global markets from regional headquarters.
This analysis examines each pillar through exclusive interviews with industry leaders, case studies of companies navigating growth challenges, and data revealing where opportunities and obstacles intersect. Understanding these dynamics matters for corporate leaders making investment decisions, policymakers shaping competitive frameworks, and professionals planning careers in a sector that will define Canada’s economic future for decades.
The Scale and Economic Impact of Canada’s Tech Sector
Canada’s technology sector has become a cornerstone of the national economy, generating over $230 billion in annual economic output and supporting more than 2.1 million jobs across the country. The ICT sector GDP and employment figures reveal that technology now contributes roughly 8.4% of Canada’s total GDP, a share that has grown steadily over the past decade while traditional resource sectors have remained relatively flat. This growth has made the tech industry comparable in economic weight to construction and significantly larger than agriculture or forestry, marking a fundamental shift in what drives Canadian prosperity.
Regional concentration shapes how this economic impact manifests across the country. The Toronto-Waterloo corridor houses the densest cluster of tech companies and talent, with over 15,000 technology firms and more than 300,000 workers spanning everything from enterprise software to financial technology. Montreal has positioned itself as North America’s AI capital, leveraging world-class research institutions and a lower cost base to attract global companies establishing AI labs. Vancouver’s tech ecosystem focuses heavily on gaming, visual effects, and cloud infrastructure, while Calgary has seen energy companies spin out cleantech and digital transformation ventures that apply technology to resource sector challenges.
The sector’s resilience through economic cycles has proven notable. During the 2020 pandemic disruption, while many industries contracted sharply, technology employment grew by 5.3% as companies accelerated digital transformation initiatives. This counter-cyclical strength, combined with higher-than-average wages (tech sector median compensation runs 60% above the national average), makes the industry’s expansion particularly valuable for economic diversification and long-term prosperity.
Artificial Intelligence and Machine Learning Leadership
From Research Excellence to Commercial Application
Canada’s world-class AI research institutions produce groundbreaking discoveries, but the transition from lab to market remains a critical juncture where many innovations falter. The pathway typically begins with academic spinouts or licensing agreements, often facilitated by university commercialization offices that have strengthened considerably over the past decade. Early-stage funding comes from a combination of angel investors, SRED tax credits, and specialized programs like the National Research Council’s Industrial Research Assistance Program (IRAP), which provides non-dilutive capital crucial for validating technical concepts.
The real test emerges during the Series A and B stages, where Canadian companies face the “valley of death” between proof-of-concept and commercial scale. Element AI’s trajectory illustrated both the promise and pitfalls: founded by leading researchers including Yoshua Bengio, the company attracted substantial investment but ultimately sold to ServiceNow rather than scaling independently. Success stories like Cohere, which retained top talent from Google Brain to build large language models in Toronto, demonstrate that retaining technical leadership while navigating from idea to enterprise requires competitive compensation, meaningful equity structures, and a compelling vision for building globally significant companies on Canadian soil. The talent retention challenge intensifies as U.S. tech giants and well-funded startups actively recruit from Canada’s AI programs, offering compensation packages that often exceed what domestic companies at earlier stages can match.
Clean Technology and Environmental Innovation
Exclusive Interview: Building Environmental Solutions at Scale
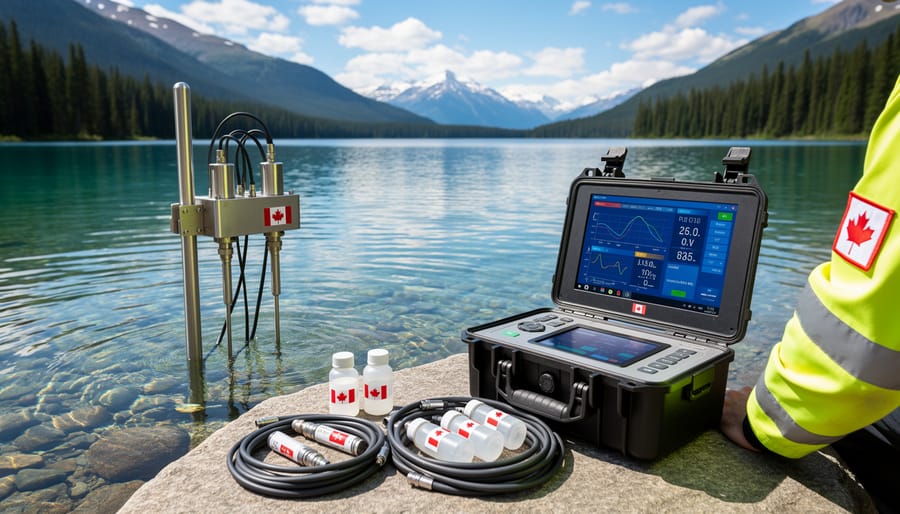
Sarah Chen, CEO of AquaTech Solutions, a Toronto-based water treatment technology company, has spent a decade transforming laboratory research into deployable systems now operating across Canada and in twelve export markets. Her company’s modular filtration platforms address industrial wastewater challenges while reducing energy consumption by forty percent compared to conventional approaches.
“The regulatory environment in Canada actually gave us an advantage,” Chen explains. “Provincial water standards forced us to design systems that exceeded most international requirements. When we approached U.S. and European buyers, our technology was already compliant with their strictest regulations, and we had five years of operational data proving efficiency gains and cost savings.”
The path to scale required navigating investor skepticism about cleantech returns. “Early venture capital conversations centered on our timeline to profitability, not our environmental impact. We learned to lead with unit economics and customer acquisition costs, then demonstrate how our environmental performance created competitive differentiation and regulatory resilience. That reframing opened institutional funding.”
Chen sees convergence opportunities between environmental technology and sectors like agriculture innovation where water quality monitoring and treatment systems address both productivity and compliance needs. “Canadian farms dealing with nutrient runoff regulations became early adopters because our systems delivered measurable environmental outcomes while protecting their operating licenses.”
Export success hinged on partnerships rather than direct sales. “We license our core technology to regional equipment manufacturers who understand local procurement processes and service requirements. That model let us enter markets we couldn’t afford to serve directly while building recurring revenue through licensing fees and data analytics subscriptions.”
Fintech and Digital Financial Services Evolution
Canada’s financial services sector has undergone a fundamental restructuring through technology adoption, creating opportunities that extend far beyond simple digitization of existing processes. The transformation encompasses new business models, regulatory approaches, and competitive dynamics that position Canadian fintech companies to serve both domestic and international markets.
Digital banking platforms have moved from challenger positioning to mainstream acceptance. Canadian consumers now access banking services through mobile-first interfaces, open banking frameworks are enabling data portability, and embedded finance solutions are integrating financial services into non-financial platforms. Wealthsimple’s growth to over 3 million users demonstrates market appetite for streamlined investment experiences, while Koho and Neo Financial have built substantial customer bases by reimagining everyday banking around transparency and rewards.
Payment processing innovation addresses both consumer convenience and merchant efficiency. Companies like Nuvei, which handles transactions across 200 markets, showcase Canadian capability in building global payment infrastructure. Cryptocurrency exchanges based in Canada navigate complex regulatory requirements while serving institutional and retail clients, and point-of-sale systems increasingly incorporate loyalty programs, inventory management, and predictive analytics alongside transaction processing.
| Fintech Subsector | Maturity Level (2026) | Key Regulatory Considerations | Primary Growth Drivers |
|---|---|---|---|
| Digital Banking | Mature | OSFI oversight, deposit insurance, capital requirements | Consumer demand for mobile services, lower fee structures |
| Payment Processing | Advanced | FINTRAC compliance, cross-border regulations | E-commerce growth, global merchant acquisition |
| Wealth Management | Growth stage | Securities regulation, advisor registration | Automated investing adoption, fee compression |
| Insurance Technology | Emerging | Provincial insurance regulation, data privacy | Usage-based models, claims automation |
| Blockchain/Digital Assets | Early development | Securities law application, AML requirements | Institutional adoption, custody solutions |
Regulatory technology has emerged as a critical subsector addressing compliance complexity. Canadian RegTech firms develop solutions for anti-money laundering monitoring, know-your-customer verification, transaction surveillance, and regulatory reporting. These tools serve both fintech startups and established institutions navigating requirements from multiple regulatory bodies across federal and provincial jurisdictions.
Cybersecurity remains paramount as financial services digitize. Canadian companies specialize in threat detection, fraud prevention, secure authentication, and incident response specifically calibrated to financial sector requirements. The sector’s collaborative approach to security, with information sharing between competitors on emerging threats, strengthens the entire ecosystem’s resilience against increasingly sophisticated attacks targeting customer data and transaction systems.
Health Technology and Digital Health Infrastructure
Canada’s health technology sector has emerged as a critical component of the country’s technology industry, generating $4.2 billion in annual revenue while addressing the unique challenges of publicly-funded provincial healthcare systems. Unlike markets with private insurance dominance, Canadian health tech companies must navigate fourteen separate health authorities, each with distinct procurement processes, data governance frameworks, and implementation timelines that shape product development from conception.
Telemedicine platforms experienced explosive growth during the pandemic but have since evolved beyond emergency response into integrated care delivery models. Companies like Maple and Dialogue now provide ongoing chronic disease management, mental health services, and specialist consultations that complement rather than replace in-person care. Provincial governments have formalized virtual care billing codes, creating sustainable revenue models while addressing physician shortages in rural communities. British Columbia’s remote patient monitoring program, for instance, now tracks 18,000 patients with chronic conditions using connected devices that transmit data to care teams in real time.
Medical device innovation represents another strength, with Canadian companies developing diagnostic tools, surgical robotics, and wearable health monitors. The regulatory pathway through Health Canada provides faster approval than FDA processes for certain device categories, creating competitive advantages for companies addressing niche clinical needs. Toronto-based firms have built sophisticated imaging analysis tools using AI to detect early-stage cancers, while Montreal companies focus on neurotechnology applications.
The sector’s defining tension remains data governance. Provincial health information custodians operate under stringent privacy legislation, PHIPA in Ontario, HIIPA in Alberta, that restricts data sharing even for research purposes. This fragmentation limits the dataset sizes available for training diagnostic AI models and complicates national platform deployment. Companies that successfully navigate these constraints build privacy-by-design architectures, implement federated learning models that analyze data without centralizing it, and invest heavily in compliance infrastructure that satisfies multiple provincial regulators simultaneously.
Talent, Investment, and Policy Framework Shaping the Sector
Canada’s technology sector draws strength from an ecosystem where talent pipelines, capital availability, and targeted policy support intersect. The framework shaping this sector extends beyond individual companies to encompass immigration systems, funding mechanisms, academic institutions, and government programs designed to accelerate innovation while addressing persistent challenges that emerge as companies mature.
The Global Talent Stream, introduced to expedite work permits for highly skilled technology workers, has reduced processing times to two weeks compared to months under standard immigration channels. This program directly addresses talent shortages in specialized roles, though retention remains complex as companies compete with U.S. compensation packages and career advancement opportunities. Universities maintain research collaborations with industry through co-op programs, joint laboratories, and commercialization offices, creating pathways from academic discovery to market application that feed emerging technology venture strategies.
Government support structures provide critical financing and tax incentives:
- SR&ED Tax Credits
- Scientific Research and Experimental Development program offering tax incentives of up to 35% on qualifying R&D expenditures, providing crucial cash flow support for early-stage companies investing in innovation.
- Strategic Innovation Fund
- Federal program supporting large-scale industrial research, technology demonstration, and ecosystem development projects with contributions typically ranging from $10 million to over $100 million for transformative initiatives.
- Innovation Superclusters Initiative
- Five industry-led clusters spanning AI, ocean technology, protein industries, digital technology, and advanced manufacturing, each funded to drive collaboration between companies, research institutions, and investors within specific sectors.
- Global Talent Stream
- Immigration pathway enabling technology companies to secure work permits for highly skilled foreign workers within two weeks, addressing acute talent shortages in specialized technical roles.
Venture capital availability has grown substantially, with Canadian firms raising $6.2 billion in 2025, yet late-stage funding gaps persist. Companies reaching Series B and beyond increasingly turn to U.S. investors, introducing pressure to relocate headquarters or establish significant American operations. The retention challenge intensifies at scale, when access to deeper capital pools, larger customer markets, and concentrated industry talent becomes decisive in growth trajectories.
Scaling Challenges and the Path Forward
The survival rate tells a stark story: most Canadian tech companies that achieve product-market fit either get acquired before reaching unicorn status or relocate core operations to the United States to access capital and talent at scale. Late-stage funding remains the critical bottleneck. While seed and Series A rounds have become more accessible through strengthened domestic venture capital, companies seeking $50 million or more typically must court American investors who often demand U.S. incorporation and presence as conditions. The resulting pattern is predictable: promising technology developed in Canada, early traction gained in domestic markets, then either a strategic sale to foreign acquirers or a gradual shift of executive teams, engineering leads, and product development south.
This brain drain operates on multiple levels. Top engineering talent faces salary differentials that can reach two or three times Canadian compensation for equivalent roles in Silicon Valley or Seattle. Executive teams building companies with global ambitions find themselves pulled toward proximity to major investors, strategic partners, and the largest customer markets. The decision calculus becomes brutal: stay Canadian and accept slower growth trajectories with limited exit options, or embrace American markets and risk losing the innovation tax credits, research partnerships, and talent pipelines that enabled early success.
Yet a counter-narrative is emerging among companies choosing to scale from Canadian headquarters. These organizations leverage Canada’s competitive advantages strategically: lower operational costs, strong technical universities as talent sources, multicultural teams that understand diverse markets, and government programs that reduce R&D expenses. They build distributed operations that maintain engineering in Canada while establishing sales presences in target markets. They cultivate relationships with Canadian pension funds and sovereign wealth managers who can provide patient capital for longer-term growth strategies. Most importantly, they protect your reputation as Canadian success stories, using that positioning to access government contracts, attract nationalism-minded investors, and differentiate in crowded global markets.
Why do Canadian tech companies get acquired early instead of scaling independently?
Late-stage funding gaps push companies toward acquisition before reaching the scale needed for independent public offerings. Domestic institutional investors remain cautious about technology sector risk, while American venture capital firms often prefer acquisition over continued funding of foreign entities.
How does Canadian venture capital compare to global funding ecosystems?
Canada performs well in seed and early-stage funding but lags significantly in growth and late-stage capital. The funding environment supports company formation but struggles to sustain high-growth trajectories through to market dominance.
What competitive advantages do Canadian tech companies actually have?
Lower operational costs, access to diverse international talent through immigration programs, strong university research partnerships, substantial R&D tax incentives, and proximity to the U.S. market without the full cost structure of American operations.
What policy changes would most strengthen Canadian tech scaling?
Expanding late-stage venture capital through pension fund mandates, reforming stock option taxation to compete with U.S. equity compensation, and creating procurement preferences that give domestic tech companies access to government contracts as anchor customers.
The path forward requires acknowledging that not every Canadian tech company needs to become a global giant headquartered in Toronto or Montreal. A healthy ecosystem includes companies that scale to sustainable regional leadership, businesses that get acquired and reinvest founder capital into new ventures, and the rare companies that build truly global operations from Canadian bases. The challenge is ensuring that third category remains viable, that acquisition becomes one option rather than the only realistic outcome, and that the talent and capital that fuel innovation continue flowing toward Canadian opportunities rather than exclusively southward.
Canada’s technology industry stands at an inflection point in 2026. The six pillars examined, AI leadership, cleantech innovation, fintech evolution, health technology, ecosystem infrastructure, and scaling realities, reveal a sector with genuine strengths and persistent challenges. Canadian companies have demonstrated they can compete globally in research excellence and early-stage innovation, yet transforming that foundation into enduring commercial success requires addressing the structural barriers that still push promising companies toward acquisition or relocation.
The opportunities ahead are substantial. Businesses across every sector need the technological solutions Canadian companies are building, from AI-driven process optimization to environmental monitoring systems that meet increasingly stringent regulations. The convergence of climate imperatives, healthcare transformation, and financial system modernization creates fertile ground for Canadian innovation to solve real problems at commercial scale.
Success depends on coordinated action. Policy frameworks must evolve beyond early-stage support to address late-stage funding gaps and talent retention. Investors need patience to build companies that scale globally while maintaining Canadian operations. Businesses themselves must prioritize ethical development alongside growth, ensuring technological advancement serves broader societal good rather than narrow commercial interests.
The technological transformation of Canadian business is underway, not pending. The question facing corporate leaders isn’t whether to engage with the technology sector, but how to leverage its capabilities while contributing to an ecosystem that can sustain long-term competitive advantage for the nation.